🎢 Rand Loses a Week in One Afternoon…and Wins Friday Back
Published 14 September 2026
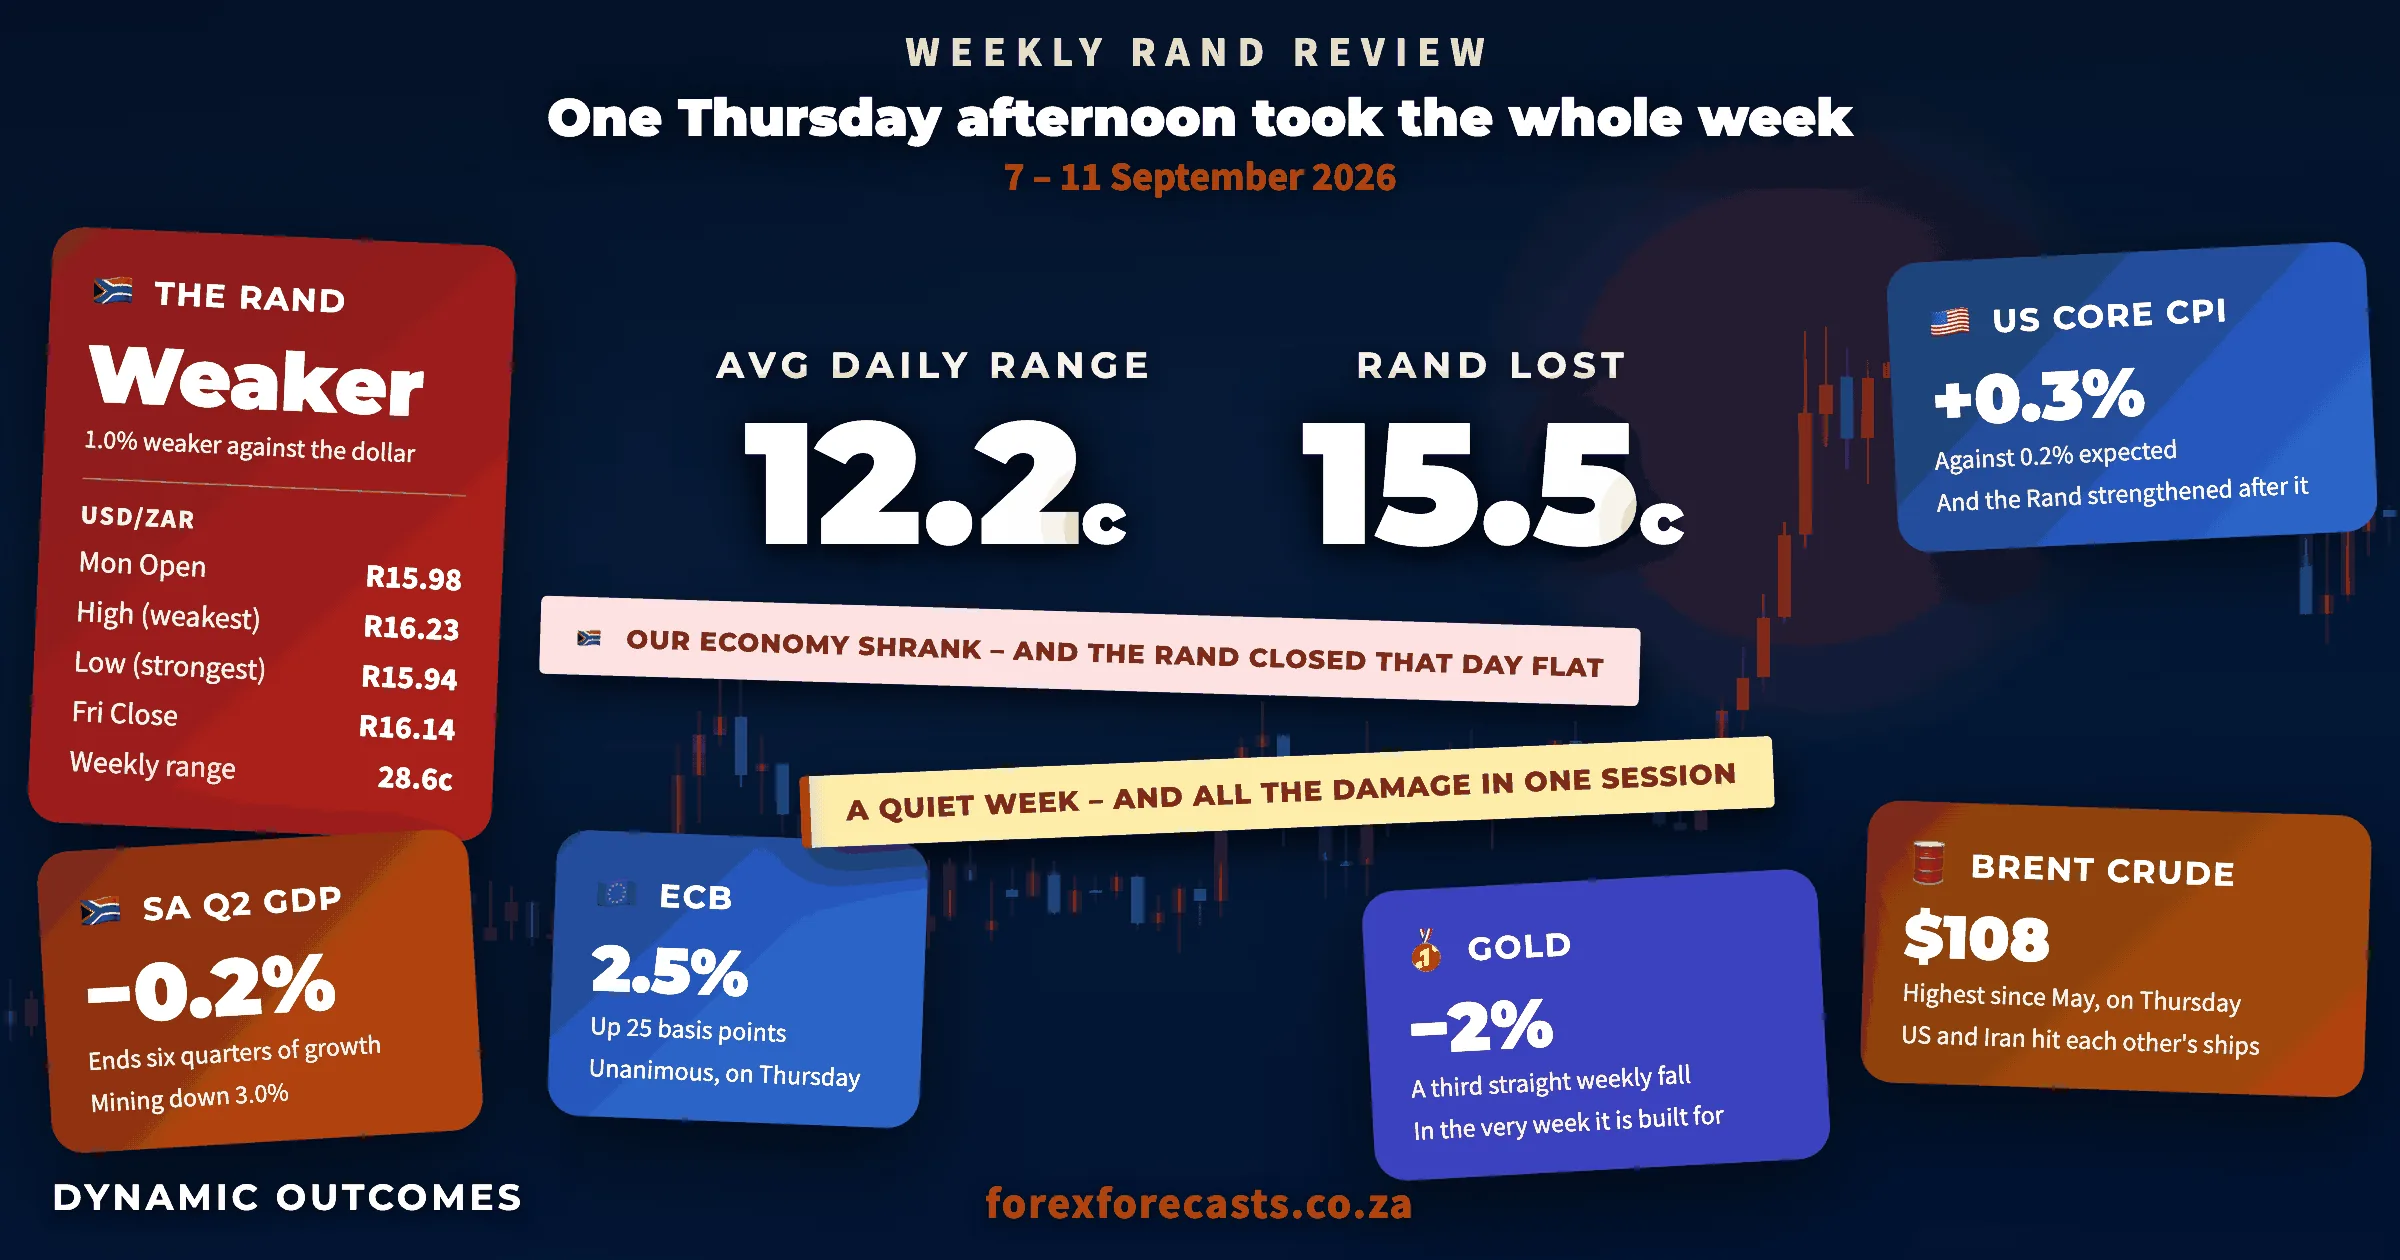
Well, that was a week where the worst domestic number in six quarters did nothing at all...
...and a single Thursday afternoon, 8,000 miles away, did the lot.
Our economy contracted on Tuesday, snapping six straight quarters of growth – and the Rand did not so much as blink.
By Friday evening it was 15.5 cents weaker at R16.14 – and that is after Friday handed a good chunk of it back.
Let's dig into it...
But first – the call we had out before any of this began.
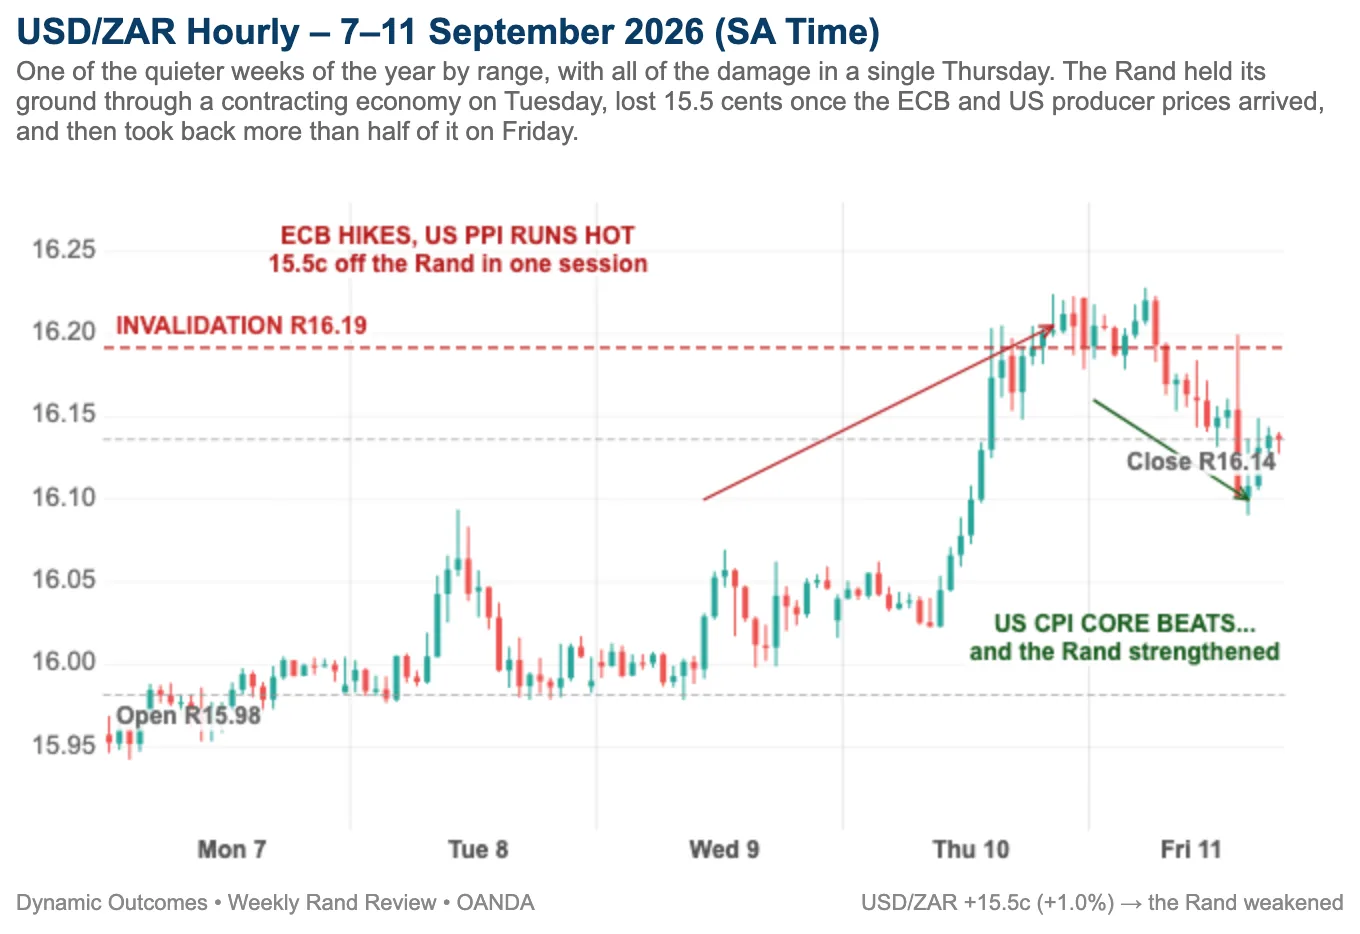
The cycles were calling the Rand lower, with an invalidation level in place at R16.19. That is the price at which we are wrong.
On Thursday afternoon the market went through it.
It went 3.6 cents through at the furthest, spent the better part of a day above it, and by Friday evening had reversed and closed the week back underneath at R16.14. Which may well make it a false break rather than a real one.
Key Moments (7–11 September 2026)
Some of the more pertinent headlines and events over the past week:
🇿🇦 Our Economy Went Backwards – And the run of growth we had all been quietly counting on ended with it.
🛢 The Gulf Went Off Again – The biggest declared wave of attacks on shipping since it began, and October's pump price is already written.
🇪🇺 The ECB Hiked Into An Oil Shock – And not one hand went up against it.
📈 Thursday Took The Entire Week – One session did more than the other four put together.
🇺🇸 US Inflation Came In Hot – In the half of the number the market actually cares about.
🥇 Gold Fell Anyway – A third straight weekly decline, in the very week it is supposed to be for.
⛽ October Looks Expensive – And the barrel that did it has not even reached our pumps yet.
Monday the Rand had a look at R15.94 overnight, which turned out to be its best level of the entire week, and then could not be bothered to do anything with it.
6.2 cents of range, an empty domestic diary, and nothing much to argue about (enjoy it while it lasts).
Tuesday brought the figure we had all been waiting for, and it was not a good one. Stats SA had the economy shrinking 0.2% in the second quarter, with mining off 3.0% – our first backward step after six quarters of growth.
And the Rand? It closed the day 0.3 cents stronger.
Now, before anyone credits the Rand with bravery, note the timing. Its weakest moment of that session came at 10am, a full hour before Stats SA said a word, so whatever was pushing it about that morning it was certainly not our GDP figure!
A contracting economy is supposed to sink its currency. But what is the reality?
The release is just the peg persons hang it on afterwards...
...and the sentiment had been moving long before anyone switched the microphones on.
Wednesday added 2.9 cents of drift and very little argument, which is quite something given what was going on in the Gulf that day (of which more below). It was waiting for Thursday.
In Other News
And in other news...
The Gulf went off again, and this time both sides were in it. It had already been building – Iran missed a US carrier group over the weekend of the 5th, and both sides traded tanker strikes in reply.
Then Wednesday made that look like a warm-up. Five more Iranian tankers gone – the crews were at least given time to get off them first – and Iran's answer was 10 ships near Hormuz, one seafarer reported dead, and missiles into a base in Jordan the US happens to use.
It was the biggest declared wave of attacks on shipping since this war started, and you did not need to be an oil analyst to work out what came next...
...Brent went through $100 for the first time since July...
...and on to over $108 by Thursday, its highest since May. Which arrives at your pump in October, because it always does. Early projections have petrol up as much as R1.99 a litre from the 7th, leaving Saffers paying for a war we have absolutely nothing to do with.
And gold went down. A war in the Gulf, oil up 10%, and the one asset the whole world owns for exactly that week fell for a third week running...
...because the herd had piled into the rate-hike trade, and it wanted dollars a great deal more than it wanted metal. So the next time someone sells you a "safe haven", ask them where the herd is standing... not what the thing is called!
And if that argument interests you, it is the whole of the current Market Demystifyer. Issue #9 – Physical vs Digital Gold – takes the comparison everyone repeats and tests it against what the two of them actually did through three separate crises. Same motive, opposite behaviour. Read issue #9 here
25 Years Since 9/11. On Friday, it is a quarter of a century since that day the world stopped in disbelief. The exchanges shut for the rest of that week in 2001 and did not reopen until the 17th, and when they did, every assumption about risk had been repriced – and quite practically, the world has never been the same since. There are persons trading today who were not born when it happened...
...and a week that turned on burning tankers is not the week to forget it.
To get back to the Rand, then, and the two days that actually decided the week.
Thursday is where the week actually happened.
The ECB moved first, hiking 25 basis points to 2.5%, and not one member of that committee could find a reason to object, which for the ECB is about as close to a standing ovation as it gets. Lagarde called the decision a no-brainer.
So there we had it. A central bank in Frankfurt putting up the price of money to deal with the price of a barrel being set, at that very moment, by missiles fired somewhere between Iran and a US carrier group – over which it has precisely no say whatsoever!
Then came US producer prices. Final demand up 0.4% on the month, energy up 4.2%, and diesel alone up 24.1%.
That last figure is the whole week in one number. The Gulf strikes turned into a barrel, and the barrel turned into US diesel, and by the time that diesel had worked its way into a US inflation figure it was suppertime in Johannesburg and the Rand had been pushed all the way up to R16.22 – before settling back to close the day at R16.19, which is to say almost exactly on our line.
The Rand lost 15.5 cents on the session which, near enough to the cent, is the whole week's damage in a single afternoon. And not a cent of it was earned here!
Mind you, here is the irony in it. In the very week the ECB actually raised rates, the euro is the currency the Rand lost the least against – 0.9%, against 1.1% to the pound.
Friday was supposed to finish the job. US consumer prices came out just after lunch our time: headline bang in line... but core at 0.3% against the 0.2% expected, which was the half the market cared about. The odds on a hike next week jumped, and the US 10-year went with them – 18 basis points in five days.
If anything, all of that says a stronger US dollar and a weaker Rand.
Instead (and this is the bit worth sitting with) the Rand spent the following hour getting stronger. Its best level of the day came at 3pm – the half hour straight after the release – and it closed the week around R16.14, having handed back more than half of Thursday's damage. It slipped a little further once our market had gone home, out at R16.12 on the New York close.
Pretty revealing, isn't it!?
The number arrived exactly as the hawks wanted it, and the market had already finished doing what it came to do.
Volatility and Risk Analysis
For those of you carrying US dollar exposure, here is what it was worth in money.
Open to Close Move: 15.46 cents
Risk per $1 Million Exposure: R154,600
Average Daily Range: 12.19 cents
Risk per $1 Million Exposure: R121,900
Maximum Single-Day Move: 20.16 cents, Thursday's range
Risk per $1 Million Exposure: R201,600
Weekly Range: 28.55 cents, R15.94 low to R16.23 high
Risk per $1 Million Exposure: R285,500
By this year's standards it was a quiet week – 30th of 37 by range. And that is exactly what makes Thursday worth your attention.
An importer who covered at Thursday's close instead of Friday's paid 5 cents more on every dollar... about R50,000 per $1 million, for the very same dollars, in one of the quietest weeks of the year!
The Week Ahead (14–18 September 2026)
SA: Our own August inflation figure is due, and it is the last one the Reserve Bank sees before the MPC meets on the 23rd. Kganyago has already called this a polyshock – oil and a looming drought turning up together .
US: The FOMC decides on the 15th and 16th. After Friday the market has all but talked itself into a hike, so watch the dissent count, not the decision!
Global: The Bank of England follows on the 17th. And the Gulf can still tear up every line of this in an afternoon. It did on Thursday.
What to watch. R16.19. Thursday went through it and could not stay there, and that is the level I will be watching again on Monday morning.
Do let me know your thoughts on this one – just hit reply, I read them all.
Two weeks, two opposite results – and neither of them decided here.
The economy you live in and the currency you price in are not the same market. They have not been for years.
To your success
James Paynter
P.S. Gold falling in the very week it is built for is not a fluke, and it is not new. The current Market Demystifyer – issue #9, Physical vs Digital Gold – is the long version of the argument above. Read Physical vs Digital Gold
P.P.S. And on the Rand: we publish the level that would prove us wrong before the week even starts, at a price, in writing. On Thursday the market went through it. By Friday evening it had handed it straight back. That is what 21 years and 8,756 scored Rand forecasts at 72.3% average accuracy gives you – a line that tells you when to stop. See the Strategic Rand forecasts
Want the full Rand cycle picture?
Register Free for Rand Forecasts