Budget Day High Gone by Friday...
...Just as Forecasted!
Published 26 October 2026
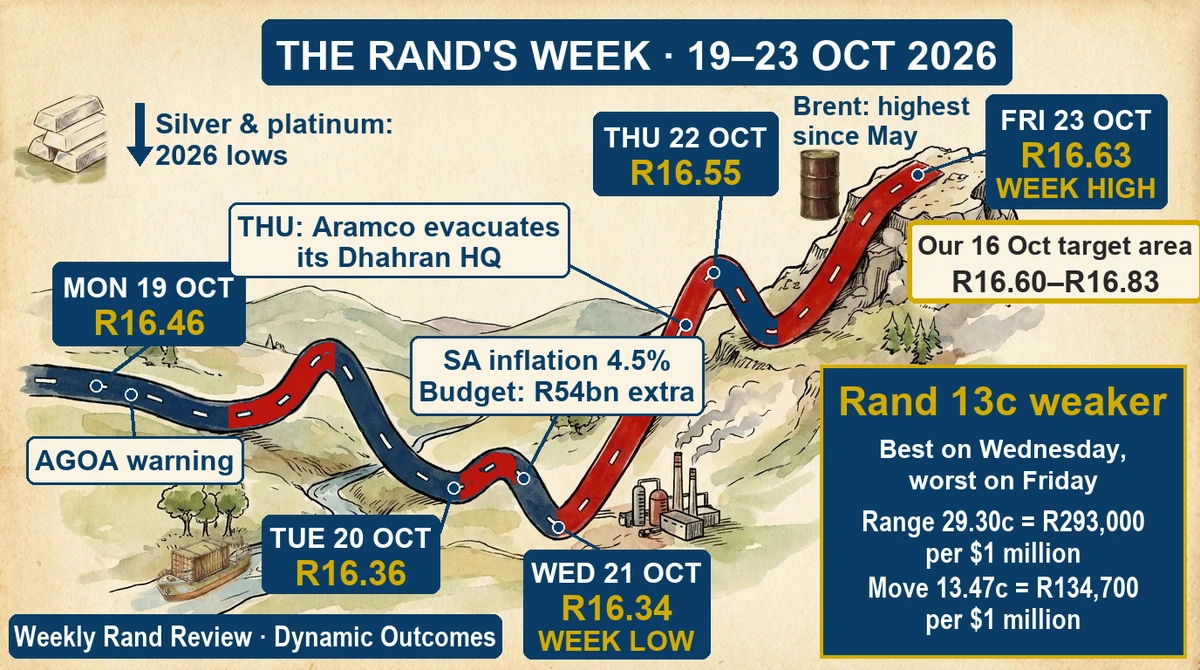
What moved the Rand last week: the Rand against the US dollar, 19 to 23 October 2026.
What moved the Rand last week?
The Gulf war reaching Saudi Arabia knocked the Rand last week. Wednesday's budget had taken it to R16.34, its best level, but once Saudi Aramco evacuated its Dhahran headquarters on Thursday and Brent climbed, the Rand handed the lot back. It finished the week of 19 to 23 October 2026 at R16.59/$, 13 cents weaker against the US dollar.
Well, by Wednesday evening the Rand had just about everything going for it...
...an extra R54 billion in the budget, an inflation number lower than feared, and its best level of the week.
By Friday afternoon it had handed the lot back, finishing the week at R16.59/$ – 13 cents weaker than where it started.
Let's dig into it...
But first – the call we put out last Friday night, before a single session had traded.
Our cycles had the US dollar heading up into an R16.60–R16.83 area against the Rand, with R16.80/83 the pivotal level. A dip below R16.40 would delay that, and a break below R16.31 would prove us wrong.
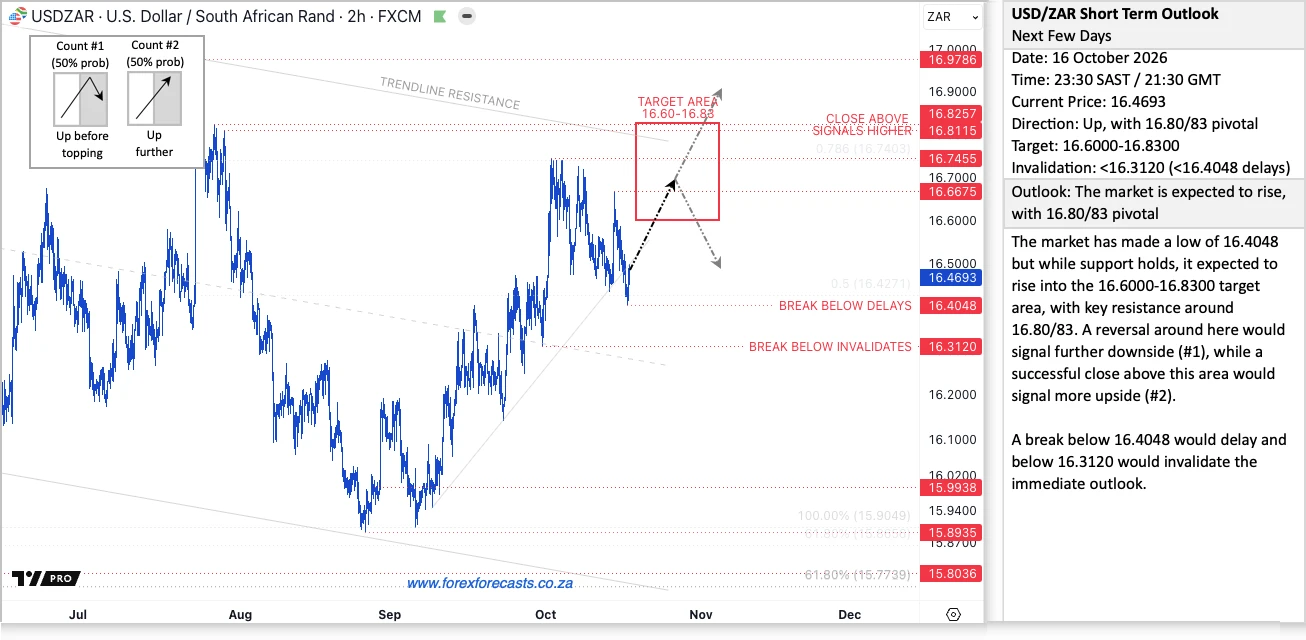
USD/ZAR Short Term Outlook, issued Friday 16 October 2026.
Key Moments (19–23 October 2026)
Some of the more pertinent headlines and events over the past week:
🇿🇦 Godongwana Finds Money He Didn't Expect – But would you bet on Treasury's numbers?
📊 SA Inflation Throws the Forecasters a Curveball – Higher or lower than they thought?
⚖️ The ANC Is Back on the Ballot – And Mbalula has a message for the DA.
🇺🇸 AGOA Hangs in the Balance – Ramaphosa tells SA to brace for a blow.
🔥 The Gulf War Reaches Saudi Arabia – And this time it's the oil itself in the firing line.
🎯 Friday Puts Last Week's Call to the Test – Read on to see how it held up.
The Rand started Monday on the front foot at R16.46/$, a couple of cents better off than last Friday's close...
...and spent the day quietly chipping away at the greenback, getting as far as R16.41.
That same day Ramaphosa told South Africans to brace for being cut out of AGOA, with Washington's decision expected within weeks.
I suspect Pretoria is finally getting the bill for years of cosying up to Moscow, Beijing and Tehran – and it's our exporters who'll be paying it.
Remember last week's ConCourt story? The court had already ruled on 15 October, ordering the IEC to put 181 ANC candidates back on the ballot in six municipalities...
...all because the party couldn't get round to pressing "submit as final" in time (you couldn't make it up!).
Fikile Mbalula wasted no time reminding the DA that "nothing binds us forever" – charming, with the local elections on 4 November.
Tuesday was more of a tug of war, with the Rand getting dragged back to R16.48 by lunchtime...
...before fighting its way back to R16.36 that afternoon.
Then came Wednesday, with two of our own big numbers on the same day.
September's inflation figure came in at 4.5% that morning, up from 4.4% but below the 4.7% the market had braced for (still well above the SARB's 3% target, mind you)...
...and the Rand barely blinked.
At 2pm Godongwana stood up with his Medium-Term Budget...
...and within the hour the Rand had found 5 cents.
Growth was cut to a measly 1.2% for the year, yet Treasury somehow found an extra R54 billion and now says debt has already stabilised at 78.4% of GDP and is falling...
...forgive me if I wait to see that one before I believe it!
There was a sweetener too – R1.50 a litre off petrol and R3 off diesel from 4 November, the very day Saffers go to the polls (make of that what you will).
In the last hour of our session the Rand pushed on to R16.34, its best level of the week, and was still holding R16.35/$ by our close.
And in other news...
The Gulf war reaches Saudi Arabia. On Wednesday Houthi rebels attacked King Fahd International Airport, killing two people, and on Thursday Saudi Aramco evacuated its Dhahran headquarters...
...and that's the world's biggest oil exporter now in the line of fire.
Washington has ordered non-essential embassy staff out of Saudi Arabia, and Brent jumped more than 4% on the week to its highest since early May (every importer paying for fuel will feel that one).
Silver and platinum sink to their lowest close of 2026. Silver gave up more than 5% on the week and platinum 5%, while gold slipped back below $4,000 for the first time since July – not what SA's miners wanted to see.
UK inflation jumps to 3.5%. It came in on Wednesday, up from 3.1%, with motor fuel almost 30% dearer than a year ago – the same oil shock, showing up in somebody else's shopping basket.
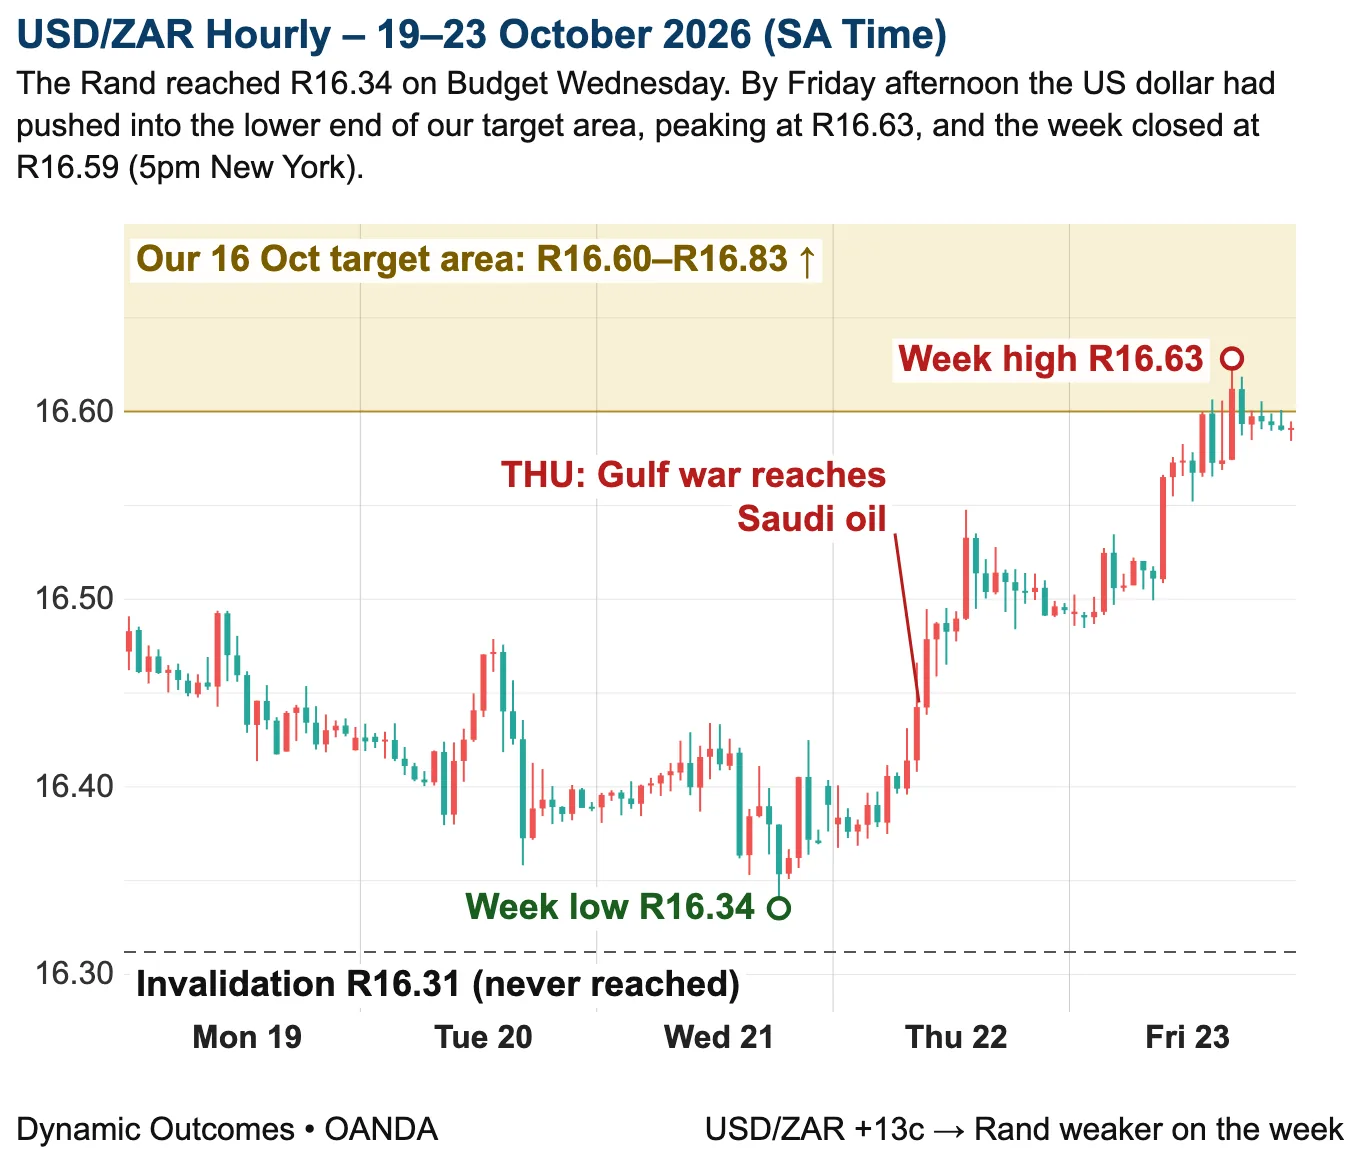
To get back to the Rand then, it had already slipped back to R16.40 by the time Thursday got going...
...and that was only the start.
The war reaching Saudi oil was the trigger, and the Rand was in no mood to fight it, giving back 15 cents in about six hours to R16.55 by early afternoon...
...though it did claw a few cents back to R16.50/$ by our close.
Friday picked up where Thursday left off.
The Rand had already touched R16.53 in the early hours, and as Brent pushed on to fresh highs the US dollar forced its way through R16.60 after lunch...
...reaching R16.63 later that afternoon, the Rand's worst level of the week.
The Rand signed off the week at R16.59/$ in US trade, 13 cents weaker than it started on Monday.
A lower-than-expected inflation figure and R54 billion of good news in the budget – and two days later? Neither counted for a thing!
And this wasn't the greenback flexing its muscles either – it actually slipped against the yen and the Chinese yuan on the week, and barely moved against the euro. No, the selling was in the Rand and its emerging-market cousins, the Mexican peso among them.
And what of our call?
It had the greenback heading up into the R16.60–R16.83 area, with a dip below R16.40 delaying the move.
The dips below R16.40 midweek did just that (without ever breaking the R16.31 that would have proven us wrong)...
...and on Friday afternoon the US dollar pushed into the lower end of our target area, at R16.63.
Just as per our forecast!
For our latest update published last week, subscribe here.
Volatility and Risk Analysis
For those of you carrying US dollar exposures, here's what the week meant in Rand terms:
Open to Close Move: The week opened at R16.46/$ Monday morning and closed Friday at R16.59/$ in US trade – a 13.47c (0.8%) weakening.
Risk per $1 Million Exposure: R134,700
Average Daily Range: 12.47 cents
Risk per $1 Million Exposure: R124,700
Maximum Single-Day Move: 18.02 cents, Thursday's range
Risk per $1 Million Exposure: R180,200
Weekly Range: 29.30 cents, R16.34 low to R16.63 high
Risk per $1 Million Exposure: R293,000
A quiet week on most days...
...but an importer who waited from Wednesday evening's R16.34 to Friday afternoon's R16.63 paid R293,000 more on every $1 million!
The Week Ahead (26–30 October 2026)
SA: Producer prices on Thursday and the trade figures towards the end of the week, with the new fuel prices kicking in on 4 November.
US: The Fed decides on Wednesday 28 October (8pm our time), followed on Thursday by the first look at US growth for the third quarter and September's PCE inflation figure.
Global: The ECB on Thursday and the Bank of Japan on Friday, with the Gulf the wildcard.
What to watch. The Fed on Wednesday night is the big one, with a hike this month still seen as the outside bet.
And for the Rand?
It's whether Friday's push into our target area is the top, or just the start of something bigger.
With the Gulf still smouldering, there'll be no shortage of triggers this week...
...but as always, it's the underlying sentiment that will decide the direction and strength of the move.
Did the budget change anything for your business? Hit reply and let me know.
To your success~
James Paynter
P.S. This week's call went out the Friday before, with the area we expected the move to reach and the level it had to hold on the way – and we've been doing it for 20+ years, across 8,672 scored Rand forecasts. See the Strategic Rand forecasts
Want the full Rand cycle picture?
Register Free for Rand ForecastsHow much extra have you been paying in fees and spreads? FX savings calculator